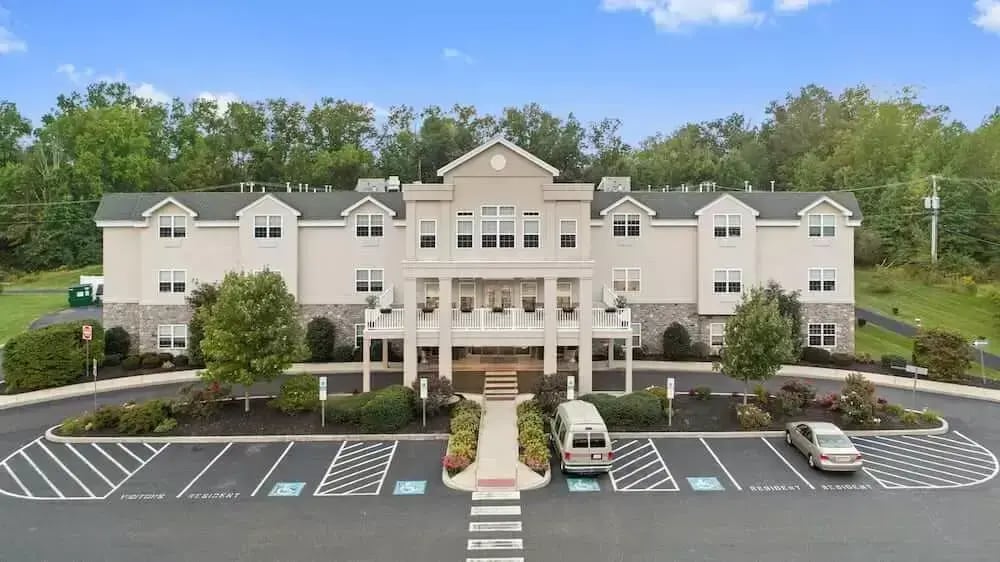
When a loved one needs more support, families often assume selling the family house is the only way to pay for senior living. For families considering Hidden Meadows on the Ridge in Sellersville, Pennsylvania, reviewing senior living financing the house fits the family’s long-term plans. This can make an early budget review especially useful.
Start With Existing Income and Insurance
Before using home equity, review income and benefits already available. Long-term care insurance may help with eligible personal care expenses, depending on the policy’s terms, benefit limits, and qualifying requirements.
- A basic financial review can include:
- Social Security and pension income
- Retirement accounts and personal savings
- Long-term care insurance benefits
- Veterans' benefits for those who qualify
- Family contributions that have already been discussed
Contact the insurer before a move and ask what documentation is required. Coverage varies by policy, so confirm what qualifies.
Explore Veterans Benefits Carefully
Eligible Veterans and survivors who receive a VA pension may qualify for Aid and Attendance if they meet additional requirements. It is not automatically available to every Veteran.
Hidden Meadows on the Ridge also has a Veterans Program that helps qualified applicants explore VA benefits and community savings. Confirm current eligibility and program terms before including them in a long-term budget.
Understand Pennsylvania Medicaid Rules
Families looking for alternatives to selling a home for care sometimes consider Medicaid. Pennsylvania Medicaid long-term services have financial and functional eligibility requirements. A primary residence may be excluded as a countable resource in certain circumstances, but that does not mean every senior living expense or personal care charge is covered.
Before transferring a house, creating a trust, or changing ownership, speak with a qualified elder law attorney. Pennsylvania reviews certain asset transfers made before an application for Medicaid long-term services.
For families considering Personal Care at Hidden Meadows on the Ridge, ask which payment sources the community accepts, and which expenses remain private pay.
Be Cautious with Home Equity Strategies
Home equity can be useful, but families should understand the consequences before using it. A reverse mortgage may become due when the last eligible borrower no longer uses the house as a principal residence, which can make it a poor fit for a permanent move.
Options to compare include:
- Renting the house and applying net rental income toward monthly expenses
- Exploring a home equity loan or line of credit if the owner qualifies
- Selling later if keeping the property remains financially manageable
Each approach can affect taxes, cash flow, estate plans, and public-benefit eligibility. Professional guidance can clarify the tradeoffs.
Compare Monthly Costs with What Is Included
Paying for senior care without selling the house also requires looking beyond the residence rate. Hidden Meadows provides chef-prepared meals, weekly housekeeping, scheduled transportation, and personalized support within Personal Care. Some may replace expenses already paid separately.
Families can also review GLOW® Memory Care if a loved one is living with Alzheimer’s disease or another form of dementia.
When comparing senior care payment strategies, ask:
- Which services are included in the monthly rate?
- Which services or support levels have additional charges?
- Are current Veterans Program savings applicable?
- How can costs change if a resident’s needs change?
A complete comparison can make it easier to determine whether you can afford personal care without selling the home.
Frequently Asked Questions
Do We Have to Sell the House to Pay for Personal Care?
No. Families may combine income, savings, insurance, eligible benefits, rental income, or other resources. The right mix depends on your finances.
Can Medicaid Let a Family Keep the House?
A home may be excluded from countable resources in some circumstances under Pennsylvania rules. Eligibility is specific, so seek professional guidance before changing ownership or relying on Medicaid.
Is a Reverse Mortgage a Good Way to Keep the House?
Not always. A reverse mortgage can become due after a permanent move, so review the loan terms before relying on this strategy.
Build a Plan Before Making a Property Decision
Keeping the family house may be possible, but the decision should reflect cash flow, eligibility, property costs, and long-term goals. Review each funding source before selling, borrowing against, renting, or transferring the property.
Schedule a tour of Hidden Meadows on the Ridge to discuss Personal Care, community services, and current pricing.